Successfully navigating a Reconsideration of Value (ROV) requires submitting objective, market-supported evidence through the lender’s official channels rather than contacting the appraiser directly. Under Appraiser Independence Requirements (AIR), loan officers and real estate agents cannot directly pressure an appraiser to hit a target number, so a structured, data-driven package is essential to bridge a valuation gap.
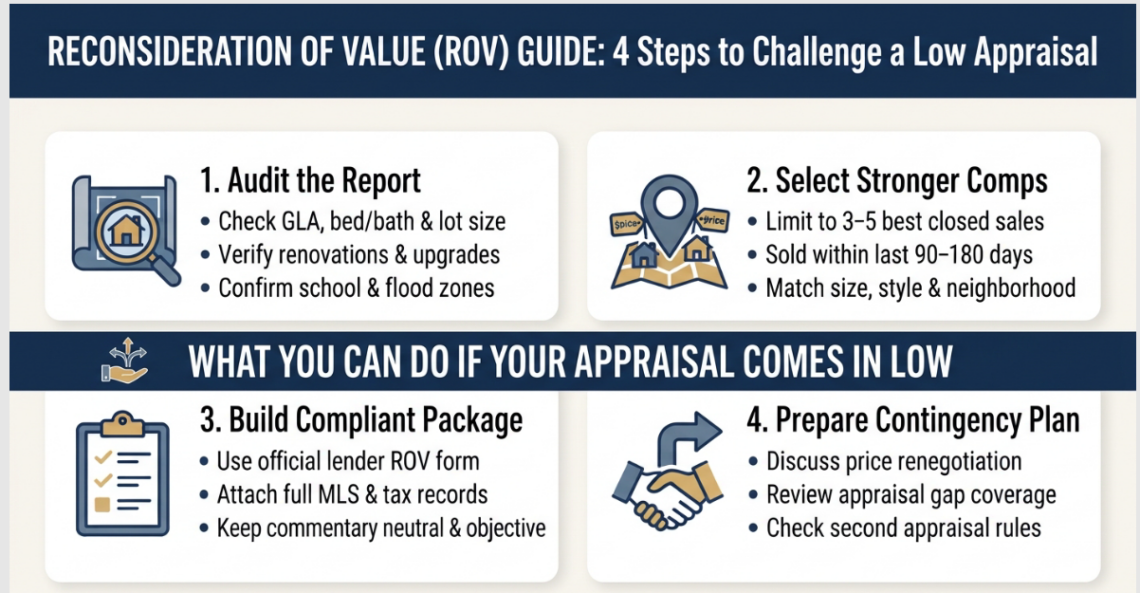
1. Audit the Appraisal Report for Factual Errors
Before gathering new market data, review the existing report line by line to identify objective inaccuracies that lower the valuation.
- Property Specs: Verify gross living area (GLA), bedroom and bathroom counts, lot size, and garage spaces against public records and floor plans.
- Condition and Upgrades: Check if recent renovations, roof replacements, HVAC updates, or high-end finishes were missed or under-credited.
- Neighborhood and Zoning: Ensure the property is classified in the correct subdivision, school district, and flood zone.
2. Select Stronger Comparable Sales (Comps)
Appraisers are bound by strict underwriting guidelines when choosing comps, so your alternative sales must meet specific criteria to be considered valid.
- Strict Limit: Submit no more than three to five of the strongest alternative comparable sales, as flooding the report with extra data often weakens the appeal.
- Recency and Proximity: Choose closed sales from the past 90 to 180 days located as close to the subject property as possible, ideally within the same subdivision or market area.
- Physical Similarity: Match the subject property’s style, square footage (within 10% to 15%), age, and lot characteristics rather than cherry-picking the highest-priced homes in the zip code.
- Pending Sales as Support: Include active listings or under-contract properties only as secondary market-trend support, since closed sales carry the primary weight.
3. Build a Compliant ROV Package
Present your findings neutrally and concisely so the lender’s appraisal desk and the appraiser can verify the data quickly.
- Use the Lender’s Form: Complete the lender’s standardized ROV request form, as most Appraisal Management Companies (AMCs) reject informal emails or unformatted notes.
- Provide Full MLS Sheets: Attach complete, unredacted MLS printouts, public tax records, and settlement data for each proposed comp.
- Write Objective Commentary: Explain briefly why each new comp is more similar to the subject property than the ones used in the original report, avoiding emotional language or references to the contract price.
- Address Original Comps: Point out specific flaws in the appraiser’s chosen comps, such as distressed sales, superior/inferior locations, or outdated closing dates.
4. Prepare a Contingency Plan
Because ROV turnaround times take several business days and success is never guaranteed, prepare parallel options to keep the transaction on track.
- Contract Renegotiation: Discuss a price reduction or a split-the-difference amendment with the listing agent and buyer.
- Appraisal Gap Coverage: Review whether the buyer can bring additional cash to closing or restructure the loan-to-value (LTV) ratio to absorb the shortfall.
- Second Appraisal Rules: Check lender guidelines on ordering a second appraisal, which is typically only permitted if the first report is proven materially deficient or biased.